Sell a house in foreclosure in Buffalo, NY — before the auction
Every Buffalo house has its own story — a family row on the West Side, a double off Hertel, a cottage by Cazenovia Park, or an East Side home that has been in the family for generations. What they share is that this is old housing, and old housing takes money to keep up. When the repairs, the taxes or the payments pile up faster than you can carry them, a straight cash sale lets you hand the house over as-is and get on with your life.
The person on this page is the person who answers the phone — no call center, no lead reselling.
Get your fair cash offer
Tell us about the property. We reply with next steps and a written cash offer, free, with no obligation.
How we help Buffalo homeowners facing foreclosure.
- 01Call as early as you can — one conversation before the demand letter keeps more options open than one after it.
- 02Receive a written cash offer that can pay off the mortgage balance at closing.
- 03We coordinate with the title company so the payoff, the paperwork and the auction date all line up.
- 04Close before the auction, so the sale — not the bank — resolves the property.
Selling a house in Buffalo: what's different locally
Buffalo's housing runs the full range — Allentown and Elmwood Village rows, Hertel Avenue doubles, South Buffalo cottages, Black Rock and Riverside fixers, and East Side houses with long family histories. Deferred roofs, furnaces and back taxes are common, and the city's long title chains turn simple sales into paperwork projects. Our office is on Bailey Avenue on the East Side, so we know these blocks and how to get a Buffalo house to closing as-is, without a repair list or a bank appraisal standing in the way.
How NY foreclosure timelines work in Erie County
New York is a judicial foreclosure state, which means your lender has to sue you in Erie County Supreme Court before the bank can take the house. That lawsuit alone can take 12 to 18 months, sometimes longer, because New York law requires a mandatory settlement conference early in the case where the court tries to work out a resolution between you and the lender. This gives homeowners more time than most states, but it also means the stress drags on longer. Once a judgment of foreclosure and sale is entered, the county schedules an auction, and that’s the hard deadline. Selling before the auction date stops the process completely; selling after a judgment is entered gets harder every week that passes.
The foreclosure timeline in Erie County, step by step
Every New York foreclosure follows the same path. Knowing where you are on it tells you how much time you have.
- 01
Missed payments and the 90-day notice
After you fall behind, your lender must send a 90-day notice before it can file a foreclosure lawsuit on most home loans. Use this window. It is the cheapest time to act.
- 02
The lawsuit is filed
The lender files in Erie County Supreme Court and serves you with a summons and complaint. You usually have 20 to 30 days to respond, depending on how you were served. Ignoring it can cost you your defenses.
- 03
Settlement conference
For most owner-occupied homes, the court schedules a mandatory settlement conference to look at loan modifications and other ways to avoid foreclosure. Learn about New York's foreclosure process and bring your paperwork.
- 04
Judgment of foreclosure and sale
If no deal is reached, the court can enter a judgment. After this point the lender is cleared to schedule an auction, and your options narrow quickly.
- 05
Notice of sale and auction
A referee sets the auction date and the sale is advertised. You can still sell the house before the auction if the payoff is covered at closing.
- 06
After the auction
The winning bidder receives the deed, and the former owner is expected to move out. Any money left after the debt is paid is called surplus and may be claimed through the court.
The best window to sell is before step 4. The more time you have left, the more choices you have.
Your options besides selling
Selling is not the only way out. Depending on your income and your lender, one of these may fit better.
Loan modification
Your lender changes the loan terms, such as the rate or term, to lower the payment. It works if you can afford the new payment.
Repayment plan or forbearance
You pause or catch up over time. It works for a temporary hardship.
Short sale
You sell for less than you owe with the lender's approval. It is slower, and the lender controls the timeline.
Deed in lieu of foreclosure
You hand the deed to the lender to cancel the debt. The lender has to agree, and you give up the house.
Chapter 13 bankruptcy
It can pause a foreclosure and set up a repayment plan. You need a bankruptcy attorney.
If keeping the house is realistic, one of these may be the better route. If it is not, selling on your own terms beats an auction. Federal guidance from HUD-approved housing counselors can help you weigh the options. If the house also needs work you cannot afford, see our page on selling a house that needs repairs.
Your options before the auction
Do Nothing
- Timeline to closeAuction proceeds (out of your control)
- Repairs neededN/A, home is lost
- FeesLegal/court costs continue
- Credit impactForeclosure stays on record 7 years
List with an Agent
- Timeline to close60-90+ days, not guaranteed
- Repairs neededUsually required before listing
- Fees6% agent commission + closing costs
- Credit impactAvoided if sold before judgment
Sell to Irish Jones Home Buyers
- Timeline to closeAs fast as 7-14 days
- Repairs neededNone, sold as-is
- FeesNo commissions, no fees
- Credit impactAvoided
Estimate
Estimate your cash-sale savings.
Move the sliders. We’ll roughly total what a traditional listing would cost you that a cash sale to Irish Jones Home Buyers skips.
Potential savings with a cash sale
$41,750
- Agent commission
- $21,000
- Closing costs (seller)
- $8,750
- Repairs avoided
- $12,000
For illustration only. Your actual offer depends on local Buffalo comparable sales and the condition of the house.
Money left after an auction: surplus funds
If a house sells at auction for more than the debt, costs and fees, the extra money is called surplus. In New York it does not go to you automatically. The funds are held, and you generally have to file a claim with the court. Many owners use an attorney for this.
Selling before the auction avoids that extra step. The sale price pays off the loan at closing, and what remains goes to you.
What to do this week
- 01
Find your most recent legal papers
The notice of sale, the judgment, or the summons.
- 02
Write down your dates
Your auction date or settlement conference date.
- 03
Ask your lender for a payoff amount
Get it in writing.
- 04
Call for free help
Reach the New York Homeowner Protection Program hotline for free legal and housing counseling help.
- 05
Get a written cash offer
Contact us for a written offer so you can compare it with your payoff.
If the house is already empty, read about selling a vacant house too.
Why sell to Irish Jones Home Buyers.
We buy as-is
Condition is our starting point, not your problem to fix first — repairs, belongings and all.
No fees or commissions
No listing agreement and no agent commission. The written offer is the number.
Close on your timeline
Cash means no bank approvals in the way — you pick the closing date that fits.
Local & licensed
A Buffalo office, a 716 phone number and NY real estate license #10491209386 you can look up.
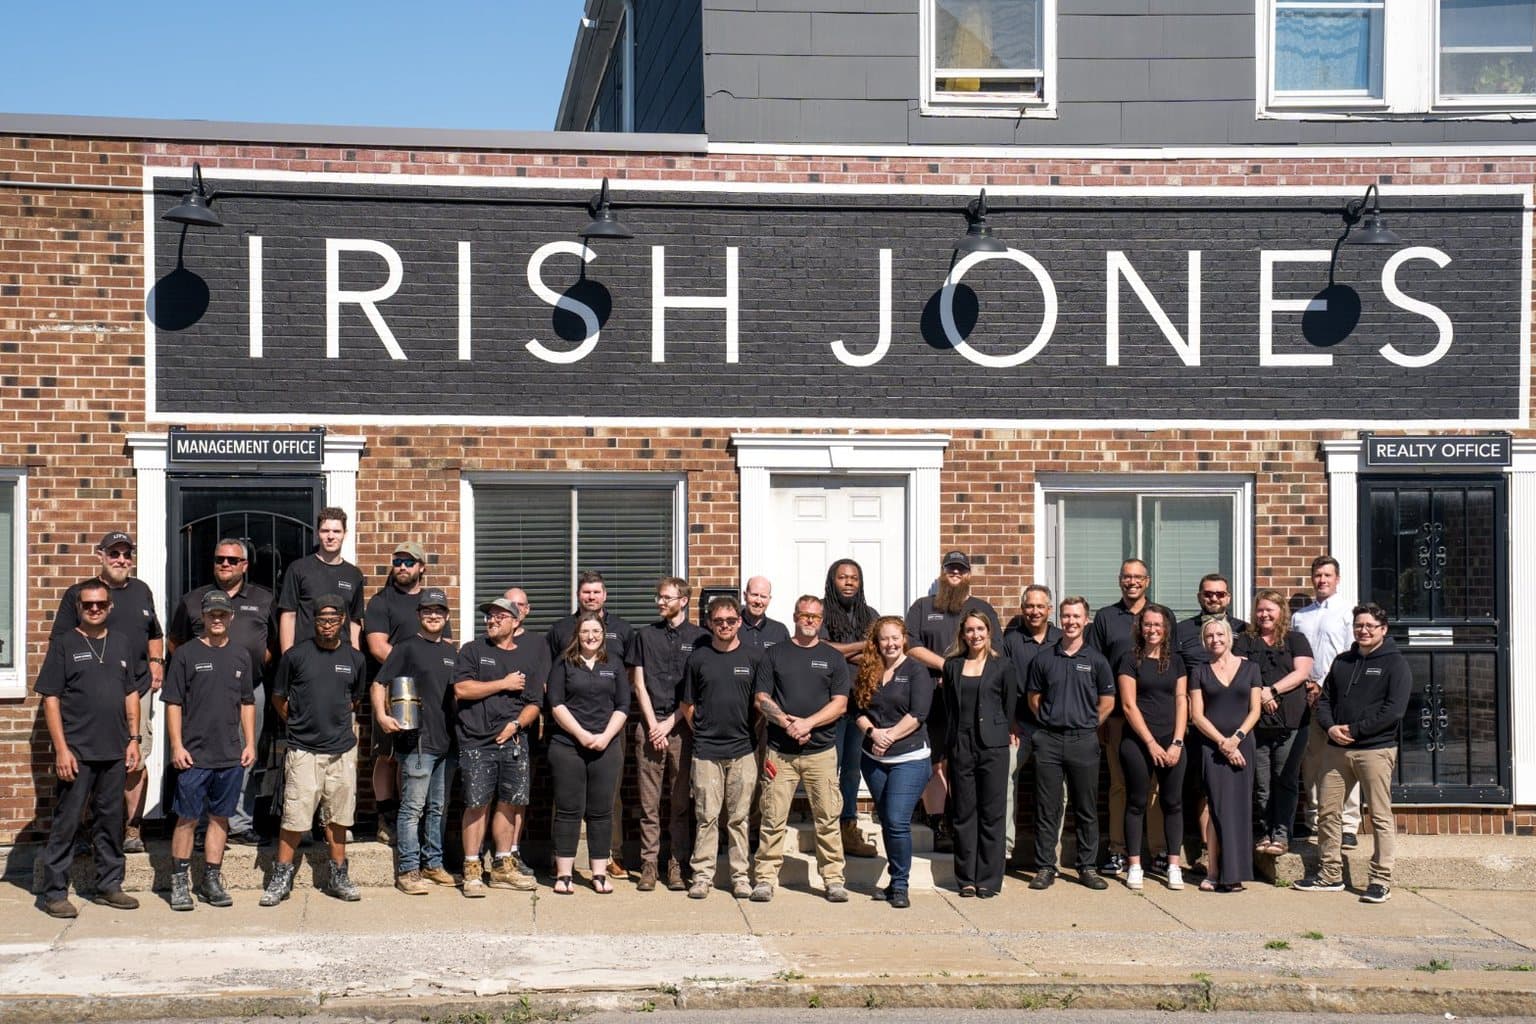
Meet the team handling your sale
Matt Irish-Jones
Co-founder & CEO, Irish Jones
NY real estate license #10491209386 · 716-768-4915
The person on this page is the person who answers the phone.
Earl Altheide
Partner, Irish Jones · Division lead, Irish Jones Home Buyers
NY real estate license #10491209386 · 716-768-4915
The person on this page is the person who answers the phone.
Quick answers.
See all questionsYes — we buy across the city, from Allentown and Elmwood Village to Hertel Avenue, South Buffalo, Black Rock/Riverside and the East Side. Every Buffalo ZIP code is inside our service area.
Yes. We routinely fold Erie County tax liens and city code items into the payoff at closing, and buy the house as-is so the repairs stay with us.
Yes, if the sale closes before the auction and the sale price covers what you owe. At closing, the title company pays off the loan from the proceeds, and the foreclosure case ends because the debt is settled. Timing is everything. The earlier we start the title work, the easier it is to close ahead of the auction date. If you have an auction date, tell us right away so we can build the schedule around it.
Tell us the balance up front. A cash sale works cleanly when the price covers the payoff and closing costs. If you owe more than the house is worth, there are other routes, such as a short sale approved by your lender, but those are slower and the lender controls the outcome. We will be straight with you about what a cash sale can and cannot cover before you spend another month on the process.
Because the purchase is cash, there is no bank approval to wait on. Once the title work is done, closing can happen within days, and we target a date ahead of your auction. Typical closings run 7 to 14 days when the paperwork is in order. Liens, probate issues or missing signatures can add time, which is why starting early matters.
Yes. New York is a judicial foreclosure state, so your lender has to sue you in court before it can take the house. In Erie County that case is heard in the Supreme Court. This is why New York foreclosures usually take longer than in many other states, and it gives you more time to respond, attend a settlement conference and consider selling.
The lawsuit alone often takes 12 to 18 months, and cases can run longer with delays, loan modification reviews or bankruptcy filings. After a judgment is entered, the sale and auction follow. Every case is different, so use your own paperwork as the guide: the dates on your notices matter more than any average. If you have a scheduled auction, treat that date as your hard deadline.
For most owner-occupied homes, New York courts schedule a mandatory settlement conference early in the case. A court representative and your lender's attorney meet with you to look at loan modifications and other options. Attending matters. You can bring a housing counselor or an attorney. It is also a good time to decide whether keeping the house is realistic or whether selling is the better path.
Often yes, as long as the auction has not happened and the payoff is covered at closing. But options narrow after a judgment, because the lender can move toward a sale date and costs and interest keep growing. Get a payoff figure, give us the auction date, and we will tell you quickly whether a closing before that date is realistic.
Selling before the auction avoids a completed foreclosure, which can stay on your credit report for seven years. Late payments already reported will remain, but a sale that pays off the loan in full generally looks better than an auction. Credit rules vary by lender, so ask a housing counselor about your situation if rebuilding credit is a priority.
Resources
Before you decide how to sell.
 Selling
Benefits of Selling Your House to a Cash Buyer in Buffalo, NY
What a cash sale skips — repairs, commissions and a lender's timeline — and which Buffalo sellers it suits.
Read more Repairs
Selling a House With Water Damage in Buffalo: Repair or Sell As-Is?
Mold, a failed ceiling and a lender who will not close. An as-is cash sale prices the damage in.
Read more Rentals
Short Term Rental Ban in Buffalo, NY: What Homeowners and Investors Need to Know
When a short-term rental can no longer operate, a cash sale is one way out without a listing.
Read more
We buy houses across Buffalo, NY.
Buffalo, NY is in Erie County, and a foreclosure there is heard in Erie County Supreme Court. If your ZIP code is below, the answer to whether we buy in your area is yes — and if it is not, call 716-768-4915 and we will tell you right away.
ZIP codes
14201, 14202, 14203, 14204, 14206, 14207, 14208, 14209, 14210, 14211, 14212, 14213, 14214, 14215, 14216, 14220, 14222
Neighborhoods & towns
Allentown, Elmwood Village, Hertel Avenue, South Buffalo, Black Rock/Riverside, the East Side
Nearby service areas: Cheektowaga · Amherst · Tonawanda & Kenmore · West Seneca · Lackawanna & Blasdell · Hamburg & Orchard Park · Niagara Falls · All service areas
Other situations we help with.
- Inherited property: estates, heirs and probate.
- Divorce or separation: sell the shared home on a plan that works for both.
- Code violations: open city notices and fines.
- Repairs it needs: sell as-is without fixing a thing.
- Vacant houses: stop paying for an empty house.
- Problem tenants: sell a rental with tenants in place.
- Relocating: moving soon? Close on your schedule.
How it works · FAQ · Contact · Home